
Q4 tends to be a busy stretch for the home improvement industry, but 2026 is shaping up to be one of the more consequential year-end runs in recent memory. In the span of about three weeks between mid-September and early October, the industry has absorbed a major executive move at one of the world’s fastest-growing power tool manufacturers, major industry consolidation, and the beginning of the holiday retail season at both national chains and independent stores alike.
Each of these developments matters on its own. Together, they’re a useful snapshot of where the industry sits heading into the year-end and where it’s headed into 2027.
1. Joe Galli Heads Up Chervon
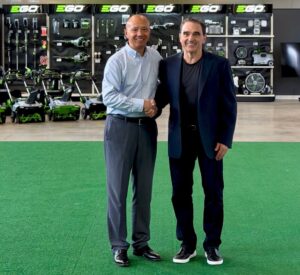
The headline story is the appointment, effective September 10, of Joseph Galli Jr. as Chief Executive Officer of Chervon Holdings — the Hong Kong-listed power tool and outdoor power equipment company behind EGO, FLEX, SKIL, and DEVON. Galli succeeds Chervon founder Longquan “Peter” Pan, who steps down as CEO but remains Executive Director and Chairman of the Board.
For anyone in this industry, Galli’s name needs no introduction. His career includes 19 years at Black & Decker, where he rose to President of Worldwide Power Tools and Accessories and launched the DeWalt brand. He later held senior roles at Amazon and Newell Rubbermaid before joining Techtronic Industries in 2006. From 2008 until his retirement in 2024, he served as CEO of TTI. His tenure was defined by turning Milwaukee into one of the world’s leading professional power tool brands and growing Ryobi into the default DIY platform.
The move is strategically significant for a few reasons. Chervon has invested heavily in cordless technology, global manufacturing scale, and brand development over the past decade, and EGO in particular has become one of the most recognized names in battery-powered outdoor equipment. At the same time, both FLEX and SKIL have faced real distribution challenges. Rebuilding retail presence while continuing to scale EGO is a two-front task, and Chervon has brought in someone with a track record of doing exactly that kind of work.
Galli hasn’t come alone. In the week following his appointment, Chervon announced two additional hires who report directly to him: Matthew H. DeFeo, Senior Vice President of Sales, Training, and Recruiting, who joined after nearly 20 years at TTI and 19 earlier years at Black & Decker; and Jeffrey P. Campbell, Senior Vice President of Industrial Commercial Sales. The pattern suggests a focused team build around professional sales, training, and recruiting.
For retailers, the practical implication is worth watching. SKIL earned a notable distribution win earlier this year with a curated assortment at Tractor Supply. If Galli can rebuild distribution for the broader Chervon portfolio while continuing EGO’s growth trajectory, the power tool aisle at every scale (chain and independent) may look meaningfully different a year from now.
2. The Consolidation Wave Keeps Rolling
The same week Chervon announced Galli, another major deal landed in the home services space. On September 2, Reuters reported that private equity firm KKR had agreed to acquire A1 Garage Door Service — a Phoenix-based residential garage door repair and replacement company — for approximately $2 billion. A1, founded in 2007 by CEO Tommy Mello, had previously taken growth capital from Cortec Group in 2022 and had grown into one of the largest residential garage door service operators in the country, working across roughly 20 states.
The A1 deal isn’t an isolated story. Earlier this year, Oak Hill Capital acquired Guild Garage Group for more than $800 million. Private equity, broadly, has been aggressively building positions in residential home services — attracted by what investors describe as predictable cash flows, non-deferrable demand (a broken garage door, a leaking water heater, a failing HVAC system doesn’t wait for the economic cycle), and highly fragmented local-operator markets ripe for roll-up.
Zoom out and the consolidation picture gets even broader. On the home builder side, the NAHB/Wells Fargo Housing Market Index tracked a doubling of merger and acquisition activity in builder markets between August 2025 and June 2026; the share of builders being approached for a deal jumped from 9% to 18%. Headline builder deals in 2026 alone include Taylor Morrison being acquired by Berkshire Hathaway, Tri Pointe Homes by Sumitomo Forestry, and United Homes Group by Stanley Martin Homes.
On the distribution side, the pattern we’ve been covering throughout the year has only accelerated: Home Depot continuing to add regional specialty distributors through SRS Distribution and GMS Inc., Lowe’s completing its $8.8 billion acquisition of Foundation Building Materials and integrating it alongside Artisan Design Group, and public roll-up players like QXO continuing to buy up roofing distribution at scale.
What ties all of this together is a strategic bet by investors and operators at every level of the industry: that the home improvement economy is a durable, essential category worth paying real multiples to own at scale.
For independent retailers, this backdrop has practical implications. Expect to see more customers (home builders, contractors) consolidated under larger operators. Expect to see more suppliers consolidated under larger distributors. Expect pricing pressure, more sophisticated procurement behavior from the newly consolidated buyers, and more aggressive private-equity-backed competitors in home services categories adjacent to retail. None of it changes the fundamental advantages that independents hold, but it does raise the stakes on executing on them.

3. Holiday Rollouts Hit the Floor
The season has officially begun. On September 29, The Home Depot announced its 2026 Holiday Decor Collection, with product rolling out in stores nationwide the week of October 5. The lineup leans into connected and interactive products, including the Grand Duchess SMART tree series, a 6.5-foot app-controlled Santa, interactive Mickey and Minnie holiday characters, and a first-ever branded holiday sweater packed with tools. Savings on gift-oriented categories like power tools and smart home products begin October 29 and run through the season.
Lowe’s holiday assortment is also drawing attention early, with Rudolph-themed animatronics (including a Sam the Snowman piece), elves, penguins, and a strong lineup of nostalgic blow molds showing up in stores and in social media previews. The theme at both retailers continues to lean toward animatronics, smart-connected lighting, and large-format outdoor display pieces — categories where year-over-year innovation drives repeat holiday purchases from the same households.
For independent retailers, the holiday assortment opportunity remains strong. Holiday décor is one of the highest-margin categories most hardware stores carry, and the customer walking in for a specific ornament, extension cord, or last-minute string of lights is reliably a basket-building visit. Co-op buying programs through Ace, Do It Best, and True Value have continued to invest in holiday assortments that compete directly with the big-box seasonal lineups, and local staging and merchandising remain a differentiator.

What It Means Heading Into 2027
Three stories, three different timelines. Galli’s work at Chervon will play out over the next 24 to 36 months and will reshape the power tool category in ways that reach every store that sells cordless. The consolidation wave is a longer-arc trend reshaping the industry at every level and is probably the single most important structural story of 2026. The holiday rollouts are the immediate opportunity, with the next 10 weeks representing one of the industry’s most important seasonal windows.
The common thread across all three: the home improvement industry heading into 2027 is simultaneously pressured and attractive. Pressured enough that operators at every level are consolidating to find scale, attractive enough that smart capital is still placing billion-dollar bets on the category. Homeowners continue to spend at near-record levels, and the retailers who serve that customer well, at every scale, continue to find real opportunities in a challenging market.
Q4 is where that opportunity concentrates. It’s also where the groundwork for 2027 gets laid.
Sources: Chervon Holdings; Power Tool Insider; Reuters; Qualified Remodeler; NAHB/Wells Fargo Housing Market Index; The Home Depot; Lowe’s Companies; Home Improvement Research Institute.